
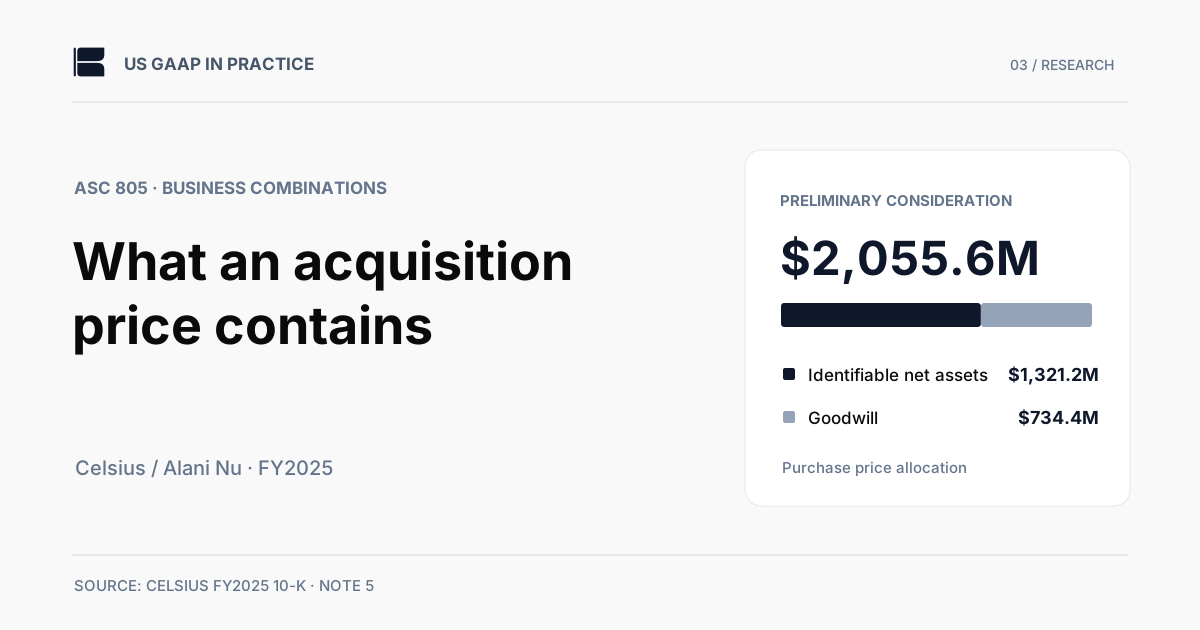
When a company buys a consumer brand, investors often focus on the purchase price and future sales potential. US GAAP asks a more exacting question: what was actually acquired, and what is each identifiable item worth? For Celsius Holdings, the 2025 acquisition of Alani Nu offers a remarkably detailed answer. The company reported $2.056 billion of preliminary acquisition-date consideration, including $1.104 billion assigned to the acquired brand and $734.4 million recorded as goodwill. These are not interchangeable accounting labels. Source: Celsius FY2025 Form 10-K, Note 5.
The purchase price tells you what Celsius gave up. The purchase price allocation shows which economic assets management believes it acquired.
One deal, several accounting questions
Celsius completed the Alani Nu acquisition on April 1, 2025, using cash, restricted shares and contingent consideration. Its FY2025 10-K gives enough detail to trace the transaction from the consideration transferred to identifiable intangible assets and residual goodwill. Under ASC 805's acquisition method, recognizable acquired assets and assumed liabilities are measured at acquisition-date fair value. Goodwill captures the excess consideration after those identifiable net assets have been measured.
That distinction matters in a branded consumer business. A brand can be separately identifiable and worth a substantial amount. An assembled workforce, expected cost savings and distribution synergies may contribute to value without qualifying for separate recognition in the same way. Calling the entire difference “goodwill” would therefore hide useful information about the acquisition economics.
Start with what Celsius actually paid
The purchase accounting table reports preliminary consideration of $2,055.589 million. It includes $1,322.425 million of cash consideration, $721.964 million of share consideration and $11.200 million of acquisition-date contingent consideration. The cash consideration disclosure includes post-closing adjustments and other specified components, so it should not be equated automatically with the cash paid net of cash acquired in the cash flow statement.
| Disclosed amount | USD millions |
|---|---|
| Cash consideration | 1,322.425 |
| Share consideration | 721.964 |
| Contingent consideration at acquisition date | 11.200 |
| Total preliminary consideration | 2,055.589 |
The filing explains that 22,451,224 restricted common shares were included in consideration. Their estimated fair value was $32.16 per share, reflecting a discount for lack of marketability relative to the quoted closing price. The earnout initially had an estimated fair value of $11.2 million, with a potential payout of $25 million depending on Alani Nu's 2025 revenue target. By year-end Celsius had remeasured it to $25 million, recognizing a $13.8 million fair value change in selling, general and administrative expense. That later remeasurement should not be confused with the original acquisition-date value.
The allocation: brands, customer relationships and goodwill
Celsius disclosed $1,321.185 million of net identifiable assets acquired and $734.404 million of goodwill, which together reconcile to the $2,055.589 million purchase consideration. Within the acquired assets, the Alani Nu brand was valued at $1,104.000 million and customer relationships at $111.000 million. The brand was assigned an indefinite useful life; the customer relationships have a five-year estimated useful life.
The bars compare selected accounting amounts, not a mutually exclusive 100% composition chart. Net identifiable assets include other assets less assumed liabilities. Brand and customer relationships are included within identifiable assets; goodwill is the residual. All acquisition-date allocations were disclosed as provisional in the FY2025 filing.
| Disclosed amount | USD millions |
|---|---|
| Net identifiable assets acquired | 1,321.185 |
| Goodwill | 734.404 |
| Total preliminary consideration | 2,055.589 |
Why the difference in useful life? The filing describes the acquired brand as indefinite-lived, while identifiable customer relationships are amortized on a straight-line basis over five years. That distinction has consequences for future earnings: customer relationship amortization is systematic, whereas an indefinite-lived brand is not amortized and instead remains subject to impairment assessment. A higher value assigned to amortizable relationships can therefore change the subsequent expense pattern even when the initial total consideration is unchanged.
What makes the allocation judgmental
Celsius valued the brand using a relief-from-royalty method: the value reflects the hypothetical royalties a market participant avoids by owning rather than licensing the brand. The inputs include anticipated revenues, royalty rates and discount rates. Customer relationships were assessed using methods that consider benefits of existing relationships and the costs and timing required to replace them.
These are fair-value estimates, not observed market prices for standalone assets. Celsius explicitly described the acquisition-date allocation as preliminary, with certain assets, liabilities and goodwill subject to further measurement-period adjustments. This makes the assumptions and the reporting date essential to any analysis. An analyst should not present the provisional amounts as final or suggest they imply a guaranteed commercial return.
$2.056B
Cash, restricted stock and contingent consideration at initial fair value.
$1.104B
Separately recognized intangible asset, with an indefinite useful life.
$734.4M
Residual value associated with expected synergies and other benefits.
A second layer: reported performance after the acquisition
Celsius reported that Alani Nu contributed approximately $1,001.9 million of revenue from the April 1 closing through December 31, 2025. It also stated that separating Alani Nu's standalone net income was impracticable because functions such as supply chain and promotional allowances had become integrated. In addition, the acquisition generated approximately $24.8 million in transaction costs recognized in SG&A rather than added to the acquisition consideration.
These disclosures limit what can be concluded from a simple purchase-price-to-revenue ratio. Acquired sales are not the same as acquired free cash flow; costs of integration, financing and intangible amortization matter. The filing also included unaudited pro forma information for comparison, which is based on assumptions and is not a forecast.
Separate consideration transferred, identifiable net assets, goodwill, transaction costs and later earnout remeasurements. For every amount, specify the acquisition date or reporting date. Do not confuse a separately recognized brand intangible with goodwill or treat provisional fair values as settled.
Why this matters for investors and finance teams
ASC 805 is not just a technical exercise. For an acquisition-heavy company, the allocation can affect future amortization, impairment exposure, comparability across periods and how analysts interpret earnings. Celsius's Alani Nu deal illustrates this vividly: a substantial amount of value was assigned to a brand that is not routinely amortized, while customer relationships carry a finite expense schedule, and goodwill remains sensitive to future business performance.
The most useful question is therefore not only whether the acquisition price looks high. It is whether the fair-value assumptions, subsequent cash generation and reporting changes support the economics implied by that price. A properly sourced purchase accounting bridge is the starting point, not the final valuation conclusion.
Behind the figures: For the evidence trail and numeric checks behind this analysis, read Behind the Figures: how the Celsius acquisition allocation was checked.
- Celsius Holdings, Inc. FY2025 Form 10-K — Note 5 (Acquisitions), Note 4 (Revenue), Item 7 and Item 1A.
- Duolingo and ASC 606: deferred revenue — related US GAAP case study in this series.
- Behind the Figures: how the Celsius acquisition allocation was checked — a separate Clarifo workflow and audit trail.
- US GAAP in Practice — series index.