Research how companies apply IFRS
Find accounting policies and notes directly in companies' reports, and compare how different companies have handled the same question.
Below is a real example: how UPM and Stora Enso value their forests under IAS 41.
Forest valuation: UPM vs Stora Enso
Quotes are from the accounting policy for biological assets in each company's FY2025 annual report (ESEF). Stora Enso files in Finnish.
Question: How do UPM and Stora Enso value their forest assets, and where do fair value changes go?
What the companies say
UPM-Kymmene
“The fair value is calculated on the basis of discounted future expected cash flows considering existing, sustainable harvesting plans and assessments regarding growth, timber prices, harvesting and silviculture costs and selling expenses.”“Own land is stated at cost whereas leased land is valued at cost less accumulated depreciation. Any changes in the fair value of the growing forests are recognized in the operating profit in the income statement.”Stora Enso
“Stora Enso soveltaa painotettuja kolmivuotisia (36 kk) keskimääräisiä markkinatransaktiohintoja, joiden katsotaan sisältävän riittävän määrän transaktioita ja arvioidaan edustavan markkinaolosuhteita raportointipäivänä.”Translation: Stora Enso applies weighted three-year (36-month) average market transaction prices, which are considered to include a sufficient number of transactions and are assessed to represent market conditions at the reporting date.
“Metsämaat arvostetaan käypään arvoon käyttämällä IAS 16 -standardissa määriteltyä uudelleenarvostusmenetelmää.”Translation: Forest land is measured at fair value using the revaluation model defined in IAS 16.
The differences at a glance
| Topic | UPM-Kymmene | Stora Enso |
|---|---|---|
| Growing trees | Discounted expected cash flows based on harvesting plans | Nordic forests: 36-month weighted market transaction prices, split between trees and land on an income basis |
| Forest land | Own land at cost | Fair value, IAS 16 revaluation model |
| Fair value changes | Growing forest changes in operating profit | Tree changes in the income statement, forest land changes in other comprehensive income |
| Fair value hierarchy | Level 3 | Level 3 |
How to run the same research
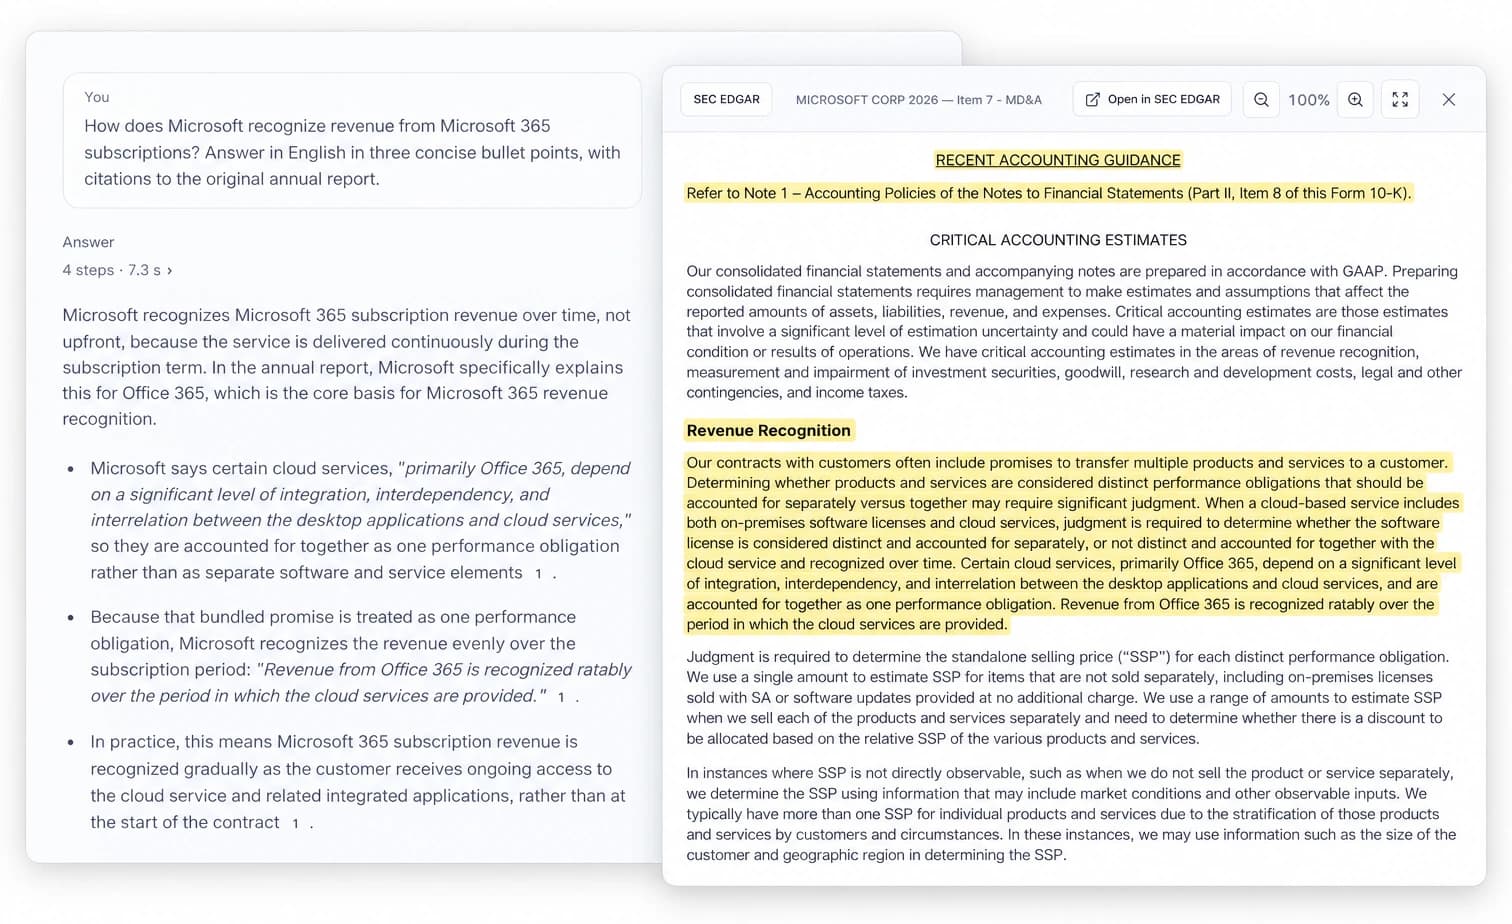
Ask about the standard
Ask in plain language, for example: "How do Nordic forest companies value their forests under IAS 41?"
See peers' own answers
The answer collects peers' accounting policies and notes directly from their reports, including Finnish-language ones.
Check the source
Every point links to the page of the report, with the quoted text highlighted.
More on this kind of work
Start a 7-day free trial.
Search filings, compare accounting policies and build source-backed analysis.
Start a free trial